Thursday, September 12, 2024

CU Economist Responds to Newest CPI Data and What it Likely Means

WASHINGTON–In August the consumer-price index climbed 2.5% from a year earlier, according to new data released by the Labor Department. That’s a decrease from 2.9% in July and marks the fifth consecutive month that inflation has cooled. Core inflation, a measure that excludes volatile food and energy costs, held roughly steady at 3.2%.

Kebede, Darwit

Dawit Kebede

"August's Consumer Price Index (CPI) report offers further evidence that inflation is moving toward FOMC’s target,” America's Credit Unions Senior Economist Dawit Kebede said in a statement. “The annualized three-month average for core CPI stands at 2.1%, despite the disproportionately high contribution from shelter, which lags behind actual market prices in reflecting the true cost of housing. This supports the argument that the Federal Reserve may not need to maintain a restrictive monetary policy, especially as the labor market shows signs of weakening, which could jeopardize a soft landing if interest rates stay elevated for too long." 

In its analysis, the Wall Street Journal said the shelter-related inflation will make it more difficult for the Fed to cut interest rates by any more than 25 basis points when it meets later this month. Some analysts have been calling for the Fed to cut rates by 50 basis points. 

Other Data Points

The Journal report noted the new federal CPI data also reveal:

  • Cost increases for food slowed in August, while used vehicles and energy were cheaper than a month earlier. 
  • An “intensifying selloff” in oil markets suggests prices at the pump will continue to decline in the coming weeks, a “key reversal in pressures that have colored Americans’ views of the U.S. economy.”
inflation 1
inflation 2

Wednesday, September 11, 2024

Here’s What Americans Have to Say About the Fed’s Anticipated Move to Cut Rates

MIAMI–After 11 interest rate increases since early 2022, the Federal Reserve is widely expected to announce a rate cut when it meets next week—but not all Americans agree that’s a good thing.

According to a new  Fed Rate Survey conducted by WalletHub, a 25-basis point rate reduction would save consumers roughly $1.87 billion in interest over the next 12 months. Some economists, including in credit unions, say a 50-basis point cut could be on the table.

WalletHub Interest Rates

To gauge public sentiment about Federal Reserve rate cuts, WalletHub said it conducted a nationally representative survey. Here’s what it said it found:

Key Findings

  • Rate-Cut Concerns: 63% of Americans are concerned that cutting interest rates will make inflation worse.
     
  • Lingering Inflation: More than nine in 10 people think inflation is still an issue.
     
  • Recession Concerns: Nearly three in four Americans are concerned about a recession.
     
  • More Worries About Inflation: Four in five people are more concerned about inflation than a recession.
     
  • Political Rate Cuts: 76% of Americans think the Fed is planning to cut interest rates for political reasons.
     
  • Skeptical of Shared Savings: Nearly two in five Americans think banks and credit unions will not pass savings from lower rates on to their customers. 

Projected Impact of a Fed Rate Cut

In its analysis of what a 25-basis point rate cut would mean, WalletHub said:

  • Consumer Savings: Credit card users will save roughly $1.87 billion in interest over the next 12 months. The company says such a cut has a 73% probability.
  • Mortgage Savings Boost: The Fed’s Sept. 18 rate cut has already decreased the cost of the average 30-year mortgage by $10,080 over the life of the loan, as mortgages have fixed rates that are priced with a far longer time frame in mind than other borrowing vehicles. 
  • Auto Loan Rate Drop: WalletHub said it expects the average APR on a 48-month new car loan to drop by around 12 basis points in the months following a 25-basis-point rate cut.

See the full results of WalletHub’s Fed Rate Survey.

Tuesday, September 10, 2024

Why CEOs Need to Plan Their Exits

 Group Of Business People Having Board Meeting Around Glass Table.

Leadership

Why CEOs Need to Plan Their Exits

Even the best execs can wear out their welcome. Smart CEOs create pipelines that build future leaders and successors.

Don’t you think it’s time you quit?

For many CEOs reading this, the answer is probably “not yet.” Though the average CEO tenure in the corporate world has stayed relatively steady in recent years, there is also a growing phenomenon of “forever CEOs,” those who’ve stayed in the job for a decade, or decades.

There are upsides to a long-tenured exec—stability, institutional knowledge, experience with common crises, and more. But there are also challenges, as a recent article in the New York Times Magazine points out: A steady hand at the helm also means a risk-averse leader who misses opportunities to innovate. The chief example of this in the article is Microsoft’s Steve Ballmer, who managed the company through a “lost decade” where it let the competition pull ahead on search, smartphones, and social media. The company stayed afloat, but it didn’t—forgive me—excel.

Apple is facing this challenge now as its current CEO, Tim Cook, nears retirement age, and every stakeholder has an idea of what a successor needs to be. “An Apple CEO needs to either be the visionary to bring new products to market, or needs to be able to find who the visionary is and partner with that visionary to bring those new products to market,” Bloomberg’s Mark Gurman recently told the Economic Times.

Even if you’re not heading out the door anytime soon, it’s crucial to be thinking about what succession planning will look like.

You don’t need to be running a company with a trillion-dollar market capitalization to be dealing with this stress. The challenge for a small-staff association executive is no different—even if you’re not heading out the door anytime soon, it’s crucial to be thinking about what succession planning will look like in your organization. That means training up your board on the issues that your organization will face in the coming years, and developing a pipeline internally that ensures there are staffers who are ultimately equipped to manage those issues.

Some organizations are taking this process to extremes: One governance expert recently told the Financial Times that some boards are so anxious around risk management and continuity that “they need a plan B and a plan C.” 

But for many organizations, the question is likely more straightforward: What will you need in the coming years that you don’t currently have? Here, the Times story has an example as well: Former Levi’s CEO Chip Bergh, who led the company for 13 years and dedicated most of his efforts around upping the brand’s cool quotient. When he planned to leave, though, he wanted “someone with new talents” and selected Michelle Gass, a retail pro.

Bergh represents what business professor Jeffrey Sonnefeld calls the “ambassador” CEO, neither the long-tenured royal nor the job-hopper. It’s the sweet spot of servant leadership—long enough to dedicate the best of your talents to making an organization better, short enough to know that the job is never up to you alone. The exact amount of time for that will different from executive to executive. But whatever that answer is, the responsible leader has the task of ensuring that they’re preparing somebody else to lead as well as they have. Even if they’re not leading the same way.

[iStock/monkeybusinessimages]

Mark Athitakis

By Mark Athitakis

Mark Athitakis, a contributing editor for Associations Now, has written on nonprofits, the arts, and leadership for a variety of publications. He is a coauthor of The Dumbest Moments in Business History and hopes you never qualify for the sequel. MORE

Got an article tip for us? Contact us and let us know!

The Off-the-Record Conversations That Need to be On-the-Record

By Frank J. Diekmann

Diekmann 2.0 Vertical

For a while now I have had a pretty good idea what someone is about to say when they begin by saying, “Off the record, Frank, but…

And then they say out loud what had previously been whispered. That is, the motto may be “people helping people,” but there is an increasing belief that credit unions aren’t helping themselves--at all—with these professional sports franchise tie-ups and with their purchases of banks that in some cases are located numerous states away and are nowhere near the home office.

And all of this it taking place with the Senate Committee on Finance this week set to hold a hearing titled “2025 Tax Policy Debate and Tax Avoidance Strategies.” While it’s not formally part of the agenda, the hearing will include among its witnesses an organization that has been beating a drum when it comes to the credit union tax exemption: Daniel Bunn, president and CEO of the Tax Foundation. 

Last week, the Tax Foundation’s Scott Hodge appeared as part of a segment on CNBC that reported on CU purchases of banks during which he said, “I think it's time to reevaluate the tax exemption that credit unions now have because they're no longer these…membership-serving organizations. They're growing and expanding and they're essentially commercial banks masquerading as nonprofits.”

The Real Problem

America’s Credit Unions was quick to respond in a letter to the Tax Foundation, sending along the usual boilerplate language around how CUs “put members first” and about the “value” of the CU tax exemption. I’m sure the folks at the foundation printed out the letter and stuck on the office corkboard with a Post-It Note urging everyone to read it and take notes.

The real problem here is the time-tested arguments of credit unions are suddenly being tested in a new and different time, and even Thomas Jefferson’s best-written and most effectively articulated letter is little more than a crumpled piece of paper when compared to all the attention being paid to the $8-mlllion-a-year deal just signed by Northwest FCU and the NFL’s Washington Commanders for naming rights to its home stadium, which is just 13 miles from the U.S. capitol, and to the ongoing acquisitions of banks by credit unions, including a deal announced last week in which a credit union in South Carolina is buying a bank 518 miles north in West Virginia. 

The Little Man & The Optics

We’ve reported on a dozen bank acquisitions so far in 2024, and NCUA Chairman Todd Harper indicated last week he knows of about another dozen that are in the works. And that deal with the Commanders is hardly a one-off; we’ve also reported in just the last week alone about credit unions in deals with the Houston Rockets, Cleveland Browns and New Orleans Saints, respectively.  The Little Man Under the Umbrella is increasingly playing (and paying) in the big leagues.

There’s more talk in one hour in Washington about “optics” than what you’ll hear during three days at an optometrists’ convention, and all of this for credit unions, as they say, ain’t good optics in DC. The Senate hearing this week is supposed to be about the expiration of tax cuts and tax policy moving forward, but you may have heard the rumor that in DC these hearings often head right off the rails as soon as the train leaves the station. Sometimes before. In this case, it doesn’t really matter if it’s accurate, the optics here play right into the “Tax Avoidance Strategies” piece of the hearing.

Get Ready for the Questions

You can bet your first week’s Fantasy Football winnings that at least one senator, whether of their own volition or at the bidding of the banking industry, is going to ask why the federal tax exemption is being used to help pay for these deals, and how the seven-figure checks being written by the people helping people people are actually helping people? 

In their letters to the Hill, America’s Credit Unions may have all the data in the world to back up noble but abstract concepts like “member value” and “community service,” and all of it may be completely true, but we live in a meme world now and a YouTube video of a CU’s name on a stadium or a TikTok of a bank’s sign being taken down and replaced by that of a credit union is what gets the eyeballs today. And if there’s one thing senators understand, like all politicians, it’s eyeballs and attention. 

Extra! Extra! They’ve Read All About It

As I’ve written here before, I’ve been told more and more often, especially over the last year, that credit unions’ long-time status as one of the untouchable third rails in Washington has been increasingly at risk as politicians show greater willingness to get mighty close to touching it, and that includes the sacred tax exemption.

That’s because in addition to the big-time sports sponsorships and bank buys, Congress and consumers have watched as the number of billion-dollar CUs has soared; have  heard reports over Navy FCU’s alleged mortgage lending practices (even if new reports eventually prove it wasn’t engaged in bias, unfortunately, those will never get the attention of the initial stories and lawsuits alleging that it was and is); have read about some big data breaches that in recent months alone have involved more than one-million members; have seen the scrutiny being given some credit unions' OD/NSF practices, and have read and heard more of the kinds of headlines that lead to putting crisis management experts on retainer.

And while they won’t talk about it, none of this is making the job on Capitol Hill any easier for the Hill advocates at America’s Credit Unions.

The Real Value of the Exemption

As I’ve written here many times before, the real value of the CU tax exemption is not now--nor has it ever been--about the federal income taxes saved. The tax exemption forces credit unions to think about what makes them different and “exempt”—and then to act in ways that support that differentiation. When a credit union is no longer different, it is, well, you know—and that’s the last thing tens of millions of Americans really need.

If there is some good news, it is that some people are willing to talk about some of these issues. I recently had a good discussion with a CEO whose credit union has been approached about putting its name on a ballpark. Many inside the credit union, he observed, are excited about the idea. It feels good to work at a place that is well-known and high profile. And these sponsorships almost always come perks, like tickets and often even a suite at the stadium, which, let’s be honest, can be enticing to some, including board members. 

The Debate to be Had

But then that same CEO shared an observation that showed the CU spirit can still be found, admitting he would have a hard time explaining to members what it was they were really getting out of having their money spent on an expensive sports naming rights deal. “It’s a lot of money,” he told me. “And I feel like we could better spend it elsewhere. Especially with our underserved members.”

That’s the debate credit unions need to be having right now. And, as uncomfortable as it’s going to be, it can’t be off the record. 

So, who’s going to say something?

Frank J. Diekmann is Cooperator in Chief of CUToday.info and can be reached at Frank@CUToday.info. Mr. Diekmann is also author of  several new book, including the brand new “The Last Lyric,” a humorous satire about a murder investigation at the Rock & Roll Hall of Fame in which every line of dialogue is either a classic pop/rock song title or lyric. Available on Amazon, Apple iBook, Barnes & Noble and Smashwords.  Mr. Diekmann is also author of a non-fiction compilation of the very best & worst he has seen and heard in covering more than 500 CU meetings and conferences, “501 Name Tags: How Everything You Need to Know About Business Can Be Learned at a Conference & Forgotten in the Trade Show.” It is available on Amazon, Barnes & Noble, Apple, Lulu, and Smashwords. 

The Unique Challenges, Opportunities for CUs in Attracting & Retaining Top Talent

Affinity FCU shares the details of its strategies, including a comprehensive benefits program.

By Pam Cohen | September 09, 2024 at 09:00 AM

person fills out job application on laptop Credit/AdobeStock

Attracting and retaining top talent is an ongoing challenge for many organizations, but credit unions face a unique set of obstacles. Unlike larger financial institutions, credit unions often operate with resource constraints and have less brand recognition, which can make it difficult to compete for top-tier talent. Despite these challenges, credit unions have unique strengths that can be leveraged to attract individuals who value a strong sense of community and a supportive work environment.

Being Innovative When Growing Talent

At Affinity Federal Credit Union, we have implemented several innovative strategies to attract and retain top talent. One key approach is our comprehensive benefits program, which emphasizes mental health and caters to the different life stages of our employees. We also offer continuous learning opportunities, including tuition reimbursement and professional development programs. Our employee referral program incentivizes current staff to bring in new talent, and our peer-to-peer recognition program fosters a culture of collaboration and appreciation.

Professional development is a cornerstone of our retention strategy. These programs enhance employees' skills, improve job satisfaction, and align their career goals with the organization's objectives. At Affinity, we blend the experience of long-time industry professionals with fresh perspectives from newer employees. We've seen this collaborative learning environment foster mutual growth and deepen employees' connection to our mission and the credit union movement.

Aligning With Organizational Values

Ensuring that our talent acquisition strategies align with our values and mission is important for fostering a cohesive workplace culture. We spend significant time engaging with our employees to ensure that our values are clearly defined and internalized. During the interview process, we use questions designed to assess candidates' alignment with our mission and values. We ask our candidates questions including what is important to you in order to be successful and fulfilled at work and encourage them to provide an example of a time when they went out of their way to delight a customer. This helps ensure that new hires not only fit the role but also resonate with our organizational culture. Consistent messaging throughout the recruitment process reinforces our commitment to our values.

Retaining Top Talent

Retention in this competitive job market requires more than just competitive salaries. We regularly review each team member's compensation to ensure it aligns with our philosophy, and we invest in continuous learning and career development opportunities. Posting job openings internally first shows our commitment to employee growth and advancement. We also conduct engagement surveys to identify areas for improvement and make necessary adjustments. Creating a supportive, engaging and rewarding workplace is key to long-term retention. We foster a sense of community through team-building activities, social events and cross-team collaboration. Most importantly, our purpose-driven work environment gives employees the opportunity to make a meaningful difference in our members' lives, which is incredibly rewarding and a gift for each of us.

Flexible Work Arrangements

Flexible work arrangements have become essential since COVID-19, significantly contributing to employee satisfaction and retention. While some jobs require a fixed schedule, others can be done when it suits employees' personal needs. Allowing employees to work when it suits them best, supported by key technologies, shows trust and adaptability. We balance remote work with necessary face-to-face interactions to maintain connection and productivity. This flexibility also enables us to extend our member service hours without overburdening our staff.

We plan to continuously review and refine our strategies for attracting and retaining top talent. Employee feedback is a key component in this process, and we are committed to delivering an excellent experience based on their insights. By staying responsive to their needs, we can ensure our strategies remain effective and relevant. By leveraging our strengths and continuously evolving our strategies, we can overcome the challenges unique to credit unions and create an environment where top talent thrives. This not only benefits our employees but also enhances the quality of service we provide to our members and the broader community.

Pam Cohen

Pam Cohen is Chief Administrative Officer for the $4.1 billion, Basking Ridge, N.J.-based Affinity Federal Credit Union.

Monday, September 9, 2024

'We've Only Just Begun'

The Federal Credit Union System is turning 90, and NCUA's Todd Harper shares four keys to CU success for the next 90 years.

By Todd Harper | September 09, 2024 at 10:00 AM

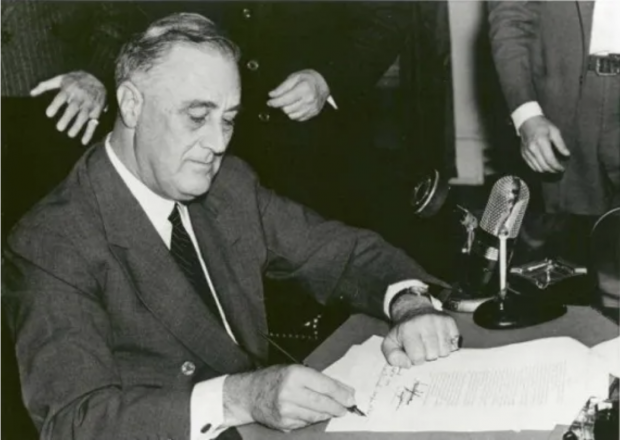
Pres. Roosevelt signs the Federal Credit Union Act into law on June 26, 1934. Credit/National Archives Pres. Roosevelt signed the Federal Credit Union Act into law on June 26, 1934.
Credit/National Archives

Ninety years ago, President Franklin Delano Roosevelt signed the Federal Credit Union Act, establishing the federal system of credit unions and increasing access to affordable financial products and services for more Americans. Since then, the system has evolved considerably from one in which credit unions offered basic savings accounts, appliance loans, and short-term credit to one that provides long-term share certificates, money market accounts, auto loans, mortgages, credit cards, commercial lending, and private student loans.

So, as we look ahead to the next 90 years and what the credit union system can become, we should mind the lessons of the immortal lyrics of the Carpenters, "We've only just begun."

Today's credit union system is thriving, and we at the NCUA need to make it even stronger and more resilient. With the financial services marketplace ever evolving, the system must continue to innovate and focus on the needs of its members, especially those of modest means. Credit unions also need to embrace transparency, fairness, vigilance, and foresight to remain successful in the years ahead.

Transparency

Transparency is the sunshine that better protects credit union members and the system, feeds efficiency, saves time, and leads to better decision-making. When credit unions and their members have good data and information, they can make better decisions, benchmark, and set themselves up for success.

In the spirit of transparency, the NCUA is developing a proposed rule that would require federal credit unions to publicly disclose information about executive compensation. All federal credit union member-owners deserve to know what their credit union leadership is paid, just like what state-chartered credit unions provide to their members and public companies disclose to their shareholders about executive pay. In addition, the NCUA's recent requirement that credit unions with more than $1 billion in assets report income from overdraft and non-sufficient funds fees on their Call Reports provides transparency into how credit unions operate and compare with their peers.

Transparency is also why the NCUA advocates for the restoration of its third-party vendor authority. When the NCUA has greater visibility into the operations of credit union service organizations and third-party vendors, we can better protect credit union members and the system and save credit unions time and money. We can also close a regulatory blind spot that threatens the nation's vital infrastructure, enabling the agency to find and address regulatory and operational harm before systemic threats evolve. After all, the best way to solve a problem is to keep it from happening in the first place.

Fairness

Credit unions were created to provide financial services to underserved populations left behind by mainstream financial institutions. If credit unions are to continue to follow this statutory mission, fairness must be their guiding principle.

That's why the NCUA joined other federal financial regulators in issuing a final rule on quality control standards for automated valuation models used by mortgage originators and secondary market issuers when valuing homes. That final rule mandates that these tools incorporate fair lending principles and adhere to quality control standards designed to comply with nondiscrimination laws.

Fairness is also why credit unions must continue to advance diversity, equity, inclusion, and accessibility, so all members have access to safe, fair, and affordable financial services. This isn't a political proposition; it's a business imperative. Diversity works. It improves organizational performance, results in better products, and strengthens the bottom line.

With their roots in providing affordable financial services to under-resourced communities, credit unions must stay focused on serving everyone regardless of race, ethnicity, gender identity, orientation, or religion. With greater perspectives in the workplace and in product offerings, credit unions can better fulfill their statutory mission, contribute to expanding the middle class, strengthen our democracy, and create a financial system that works for all.

Vigilance

In today's complex and quickly changing economy, credit union executives, leaders, and boards must exercise active, not passive, management. Considering the economic, financial, and technological challenges on the horizon, credit unions must remain vigilant in managing all risks.

Cybersecurity risk, for example, is increasing. Last November's FedComp outage and the widely reported ransomware attacks on various credit unions this year are reminders of what's at stake. Members have lost access to funds; faced bounced payment, late-payment, and overdraft fees; and had their credit scores negatively affected. Cyberattacks are a matter of when, not if, and credit unions must be prepared.

Vigilance also means the responsible stewardship of financial institutions. The failures of Cal State 9 Credit Union and Western Corporate Federal Credit Union demonstrate the unsustainable costs of incentivizing short-term gain. To address this problem, the NCUA Board approved a proposed joint agency rule on incentive-based compensation that will align executive incentives with the long-term stability of the financial institutions they manage. This proposal, required by statute, will help billion-dollar-plus credit unions avoid a repeat of the financial crisis 15 years ago.

Foresight

Finally, foresight is needed to address the longstanding consolidation trend that challenges the credit union system. A credit union board's failure to plan for the transition of its management and key decision-makers comes with high costs, including the potential for an unanticipated merger when key personnel depart, especially in smaller credit unions.

To address this concern, the NCUA Board recently reproposed a rule that would require all federally insured credit unions to have a tailored succession plan — depending on the credit union's size, complexity, or risk of operations — that covers the board of directors, the supervisory committee, and other officials. Like cyberattacks, a change in leadership is a matter of when, not if, so credit unions must be prepared.

Keys to Success

Transparency. Fairness. Vigilance. Foresight. These are the keys for the next 90 years of credit union success, and these north stars align with the seven-generation stewardship principle. This widely used management concept, which traces back to the Iroquois Nation, holds that leaders should look ahead seven generations to determine the impact of their choices on their descendants. If a choice will lead to positive outcomes and promotes overall well-being over that long term, then it's an action worth pursuing.

And, by doing just that — as a regulator and as an industry — we'll be following the advice given to us by the Carpenters, "So many roads to choose. We'll start out walkin' and learn to run. And yes, we've [only] just begun."

Friday, September 6, 2024

NCOFCU 2024 Annual report

Federally Insured CU Net Income Drops 10.1% -- FDIC-Insured Banks Net Income, Up 11%

 Credit Unions Income Down

ALEXANDRIA, Va.— Even with assets growing, net income ($15.7 billion) at federally insured credit unions was down $1.8 billion, or 10.1%, in the first half of 2024, compared with the first half of 2023, NCUA’s Quarterly Credit Union Data Summary shows.

During a call with the press, NCUA Chairman Todd Harper attributed some of the decline to CUs increasing loan loss reserves.

Harper Todd

Todd Harper

NCUA’s data also show the delinquency rate at federally insured credit unions was 84 basis points in the second quarter of 2024, up 21 basis points from one year earlier. The net charge-off ratio was 79 basis points, up 26 basis points compared with the second quarter of 2023. Insured shares and deposits rose $36 billion, or 2.1%, over the year ending in the second quarter of 2024, to $1.76 trillion.

Harper acknowledged the net income drop is “concerning.”

“However, some of it is the result of greater reserving for losses, which has decreased income,” Harper said. “But it's something that we have to watch quite carefully.”

Similarly, Harper also said the agency is watching the increase in delinquencies, noting the delinquency ratio is the highest since 2014, adding that auto loan delinquencies are up 16 basis points, year over year, to 83 BPs.

Overall, total assets in federally insured credit unions rose by $79 billion, or 3.5%, over the year ending in the second quarter of 2024, to $2.3 trillion, according to NCUA, which also acknowledged that the industry is facing some balance sheet challenges -

Continue READING


Banks Income UP

WASHINGTON— The nation’s 4,539 commercial banks and savings institutions insured by FDIC reported aggregate net income of $71.5 billion in second quarter 2024, an increase of $7.3 billion (11.4%) from the prior quarter, according to new data from the agency.

The FDIC said a decline in noninterest expense and one-time gains on equity security transactions contributed to the quarterly increase. The results were included in the FDIC’s latest Quarterly Banking Profile released today.

Here is how the FDIC insured banks performed by category:

The Industry’s Net Income Increased From the Prior Quarter, Driven By Lower Noninterest Expense and One-Time Gains

Contributing to the more than $70 billion in net income was a decline in noninterest expense (down $3.6 billion, or 2.4%) along with higher noninterest income (up $1.2 billion, or 1.5%) and higher gains on the sale of securities (up $937 million) were the primary factors driving the increase in net income, the FDIC said, adding that higher provision expenses offset some of the increase in net income.

“The quarterly increase in net income was largely driven by nonrecurring items including an estimated $4 billion reduction in reported expense related to the FDIC special assessment, approximately $10 billion in gains on equity security transactions by large banks, and the sale of an institution’s insurance division that resulted in an after-tax $4.9 billion gain,” the FDIC said. “These increases were partially offset by several large banks selling bond portfolios at a loss and a $2.7 billion increase in provision expense.”

FDIC Chart

ROA

The banking industry reported an aggregate return-on-assets ratio (ROA) of 1.20% in second quarter 2024, up 12 basis points from first quarter 2024 but down one basis point from first quarter 2023. -

Continue READING

Wednesday, September 4, 2024

PARC Compensation Consulting Launched to Deliver World-Class Service to Credit Unions and Other Non-Profits

FOR IMMEDIATE RELEASE

For more information, please visit www.PARCcompensation.com or contact:

Bruce D. Smith
Partner, PARC Street Group
(516) 639-0556
bsmith@parcstreetpartners.com

PARC Compensation Consulting Launched to Deliver World-Class Service
to Credit Unions and Other Non-Profits

 Syosset, NY – September 4, 2024 – PARC Street Group is thrilled to announce the launch of its latest strategic venture, PARC Compensation Consulting. The launch signals a significant expansion that will elevate and expand PARC Street Group’s capabilities. PARC Compensation Consulting will deliver world-class compensation consulting services to credit union industry clients and other non-profits.

 This natural extension of services is an answer to the requests of many current clients of PARC Street Partners, a leader in the Supplemental Executive Retirement Plan (SERP) space. 

 As part of this exciting development, PARC Compensation Consulting has acquired the intellectual capital of Cardwell Consulting, a respected leader in executive compensation for over 20 years. The acquisition marks a key milestone in PARC Street Group’s growth strategy, bringing a wealth of expertise and innovative solutions into our portfolio.

 In addition, PARC Street Group is pleased to share that Alan Dick, president of Cardwell Consulting and a veteran in the compensation industry, has signed a long-term consulting agreement with PARC Compensation Consulting. Alan's extensive experience and deep understanding of the compensation landscape will be invaluable as PARC Street Group expands its services and continues to provide tailored solutions to its clients.

 “After working with PARC Street Partners for several years as a consultant, I am excited to work with PARC Street Group as they expand to directly offer independent compensation consulting services.  Through this partnership, I look forward to offering a seamless transition opportunity to Cardwell Consulting’s long-term clients,” Dick said.

 In addition, PARC Street Group is excited to announce the hiring of John-Paul (J.P.) O’Connor, formerly with DDJ Myers, who joins us as a key member of our consulting team. O’Connor brings a strong background in data analysis and research and compensation consulting, making him a perfect fit for PARC Street Group’s growing team. His personal mission is to bring value to clients by providing the most current and reliable compensation data based on market trends and analysis.

 “Our expansion into total executive compensation with the launch of PARC Compensation Consulting represents a significant step forward for PARC Street Group,” said Christopher Jones, Partner of PARC Street Group. “By bringing together the expertise of Cardwell Consulting and the talents of industry leaders like Alan Dick and J.P. O’Connor, we are positioning ourselves to offer unparalleled service and insight to the credit union industry.”

 Tim Green, President of F&A Credit Union in California, a client of both Cardwell Consulting and PARC Street Partners, said: “I have worked with both PARC Street Partners and Alan Dick/Cardwell Consulting for many years and can state they are both best in class at what they do. Both firms bring an unmatched level of knowledge and integrity to their respective areas of expertise, and a combined entity will only create greater synergies for the credit union community. F&A Credit Union has relied on both PARC Street Partners and Cardwell Consulting to deal with some of our most sensitive and impactful executive compensation issues, and we could not be happier with the outcome they have helped us achieve. This merger will strengthen PARC Street Group and the industry, and we wholeheartedly support this combination.”

PARC Compensation Consulting will operate with the same commitment to excellence that has defined PARC Street Partners. The focus will be on delivering customized compensation strategies that align with the evolving needs of today’s organizations.

 Mike Lawson with CU Broadcast recently chatted with the team from PARC Street Group.  Check out the interview here - PARC Compensation Consulting Interview. 

 **About PARC Street Group** PARC Street Group is a leading consultancy that provides specialized services across a range of sectors. Focusing on delivering innovative and practical solutions, it has built a reputation for excellence and client satisfaction.

 **About PARC Street Partners**

The team at PARC Street Partners has spent decades serving credit unions that want to attract and retain top talent through benefits packages that motivate their leaders without burdening their members’ resources.

 As experts in Supplemental Executive Retirement Plans (SERPs) and Collateral Assignment Split Dollar (CASD) plans, they design benefits packages that credit unions can afford, and leaders can’t afford to miss out on.

 Their experience has helped them learn the plans that help credit unions the most. That experience, along with our commitment to radical service (lightning responsiveness, extreme customization, white-glove support), have made them a trusted resource. They are relied upon by the hundreds of clients that call them partners.

 **About Alan Dick**

Alan Dick is an advisor to boards, CEOs and board committees in a wide range of industries, including credit unions. His consulting focus is on total executive compensation with particular emphasis on executive retirement benefits.

Because Cardwell Consulting has never sold products nor accepted sales commissions, Dick frequently serves as an unbiased source to evaluate products proposed by other vendors in the marketplace.

 Prior to joining Cardwell Consulting in 2003, Dick spent nearly seven years with Invesmart Inc. and its predecessor firm, where he was responsible for the leadership of all service and operations offices nationwide. Previously he spent 15 years with Towers Perrin, where he was a principal and managed the benefits and retirement practice for the Seattle office.

 Dick is a Fellow of the Society of Actuaries, and an Enrolled Actuary under ERISA. He graduated from the University of Washington with a bachelor’s degree in mathematics.

 **About J.P. O’Connor**

John-Paul (J.P.) O’Connor is a seasoned executive compensation consultant with a deep commitment to aligning compensation strategies with organizational goals and employee well-being. With a decade of experience in data-driven analysis and a passion for impactful decision-making, he has developed a reputation for crafting compensation solutions that resonate at every level of an organization. O’Connor’s expertise lies in understanding compensation's critical role in shaping organizational culture, driving engagement, and securing long-term success.

Throughout O’Connor’s career, he has been at the forefront of guiding organizations through complex compensation challenges. His innovative approach and dedication to fairness have consistently delivered effective and strategic outcomes, ensuring that compensation decisions meet and exceed organizational objectives. O’Connor believes that well-structured compensation strategies can transform lives, empower teams and strengthen the future of organizations.

 O’Connor graduated from the University of Connecticut with a bachelor’s degree in psychology with a specialization in Neuroscience. He also has a Compensation Studies Certification from Cornell University.

For more information, please visit www.PARCcompensation.com or contact:

Bruce D. Smith
Partner, PARC Street Group
(516) 639-0556
bsmith@parcstreetpartners.com

 Tammy O’Hara, CCUE, CLU®, CCD | Executive Benefits Consultant

voice only  321.689.5822 | text only  321.415.9947 |

3453 McLain Preserve Point, Sanford, FL 32771

tohara@PARCstreetpartners.com | LinkedIn


Tuesday, September 3, 2024

‘Soft Landing’ of Economy Appears More Likely, New Analysis Suggests

WASHINGTON–The U.S. economy grew more than previously thought in the second quarter, data released Thursday shows, “bolstering the case that the country may be experiencing a so-called soft landing,” according to one new analysis.

Gross domestic product grew at a 3% seasonally and inflation-adjusted annual rate, the Commerce Department said in its revised estimate. That is up from the 2.8% rate reported last month, and it is far above the first quarter’s weak 1.4% expansion.

economy

Initial jobless claims for the week ended Aug. 24 also fell slightly, according to the Labor Department, another positive sign for the health of the U.S. economy, noted the Wall Street Journal in its analysis of the newest data.

‘All But Certain’

“Despite the economy's strength, Federal Reserve policymakers appear all but certain to begin cutting rates when they next meet in September,” the Journal stated. “Recent data show that inflation continues to cool, while the labor market shows some signs of weakness. The central bank has indicated that it is prepared to cut rates for the first time in years.”

Credit union economists have also predicted the Fed is also all but certain to cut rates at its meetings next month.

Housing Market Recover Still a Ways Off

The Journal did note that a housing-market recovery is “still a ways off, even as lower mortgage rates and higher inventory have improved conditions for potential buyers.”

Pending home sales, a measure of transactions that have gone into contract but not yet closed, fell 5.5% in July from the month prior and fell 8.5% from July of last year, the National Association of Realtors said.

New IRS Auto Loan Reporting Rule Creates Major Compliance Challenge for Credit Unions

Credit unions that make auto loans need to begin preparing now for a significant new IRS reporting requirement that could create an especial...