Friday, September 29, 2023

'It’s Been Quite a Journey': Senate Committee Passes Cannabis Banking Bill

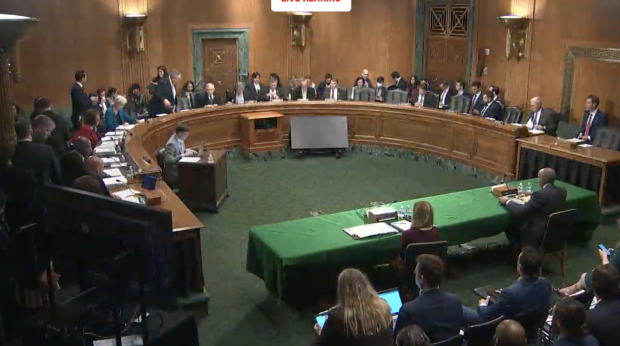
Image from Senate Banking Committee hearing on Sept. 27, 2023.

U.S. Sen. Sherrod Brown (D-Ohio) summed up the work to get the Secure and Fair Enforcement Regulation (SAFER) Banking Act passed through the Senate Committee on Banking, Housing and Urban Affairs in five words: “It’s been quite a journey.”

Committee members passed the bill with a 14-9 vote Wednesday morning. The SAFER Banking Act legislation opens banking services to marijuana businesses – an issue credit unions have struggled with for years.

The bill in its current form, which was introduced last week by a group of bipartisan senators, is an updated version of the CUNA and NAFCU-supported SAFE Banking Act, which was introduced earlier this year.

During the hearing, Sen. Brown said, “Cannabis banking is just one part of the necessary conversation about marijuana policy. There’s still much work that needs to be done.”

He added, “Cannabis policies look different in different states, but legal cannabis small businesses and their employees are running into many of the same issues. One of these issues is access to financial services.” This bill “will make it safer for legal cannabis businesses and service providers to operate to protect their workers, first and foremost, to operate in their communities.”

In a statement released after the hearing, CUNA Deputy Chief Advocacy Officer for Federal Government Affairs Jason Stverak said, “We thank the committee for moving forward on this important legislation to bring consistency and common-sense to the intersection of banking regulation and legal cannabis businesses. This bill will allow credit unions to lawfully serve these businesses and addresses the serious public safety issue of forcing these businesses to deal in only cash.”

NAFCU SVP of Government Relations Greg Mesack also released a statement, which said, “After today’s committee passage of the SAFER Banking Act, NAFCU thanks Senator Brown and members of the Senate Banking Committee for their leadership on this issue and willingness to make changes to address concerns raised by credit unions and other community financial institutions. This legislation is necessary to protect credit unions and the communities they serve in states where legal cannabis businesses are seeking financial services. It will help reduce risks by providing some legal clarity and expanding access to deposit accounts and other financial products. NAFCU looks forward to continuing the conversation as the bill moves forward to a full body vote.”

Sen. Brown said he looks forward to sending this legislation to the Senate floor. There was no timetable announced for when that might occur.

Thursday, September 28, 2023

What to Know About EV Lending

 By Ray Birch

WEST WINDSOR TOWNSHIP, N.J.—There are a couple of important facts credit unions must keep in mind as they increasingly make loans for electric vehicles (EVs).

The first is that while EVs are perceived to be more economical than internal combustion engine (ICE)-powered vehicles, one new report suggests that while electric vehicles are cheaper to operate, the overall savings may not be as significant as many people think.

Moreover, as EVs become the dominant form of transportation, prices for charging—even at home—will begin to rise just like gas prices, one automotive industry expert is predicting.

Feature EV Vs. ICE

Sumit Chauhan, co- founder and COO at Cerebrum X, which provides AI-driven automotive data services and a management platform, said that kind of conventional wisdom-challenging pieces of information must be considered by auto lenders both for the sake of their own portfolios as well as the sake of members’ household budgets.

“It's not yet cheaper to charge many electric cars than it would be to fuel their gas-powered counterparts,” said Chauhan, citing a study from Anderson Economic Group. “The cost of filling up at a gas station versus plugging in—and whether those two match up—largely depends on the vehicle segment and price.”

What Report Found

The report calculated driving costs for vehicles driving 12,000 “purposeful” miles per year in the Midwest and Michigan. The study took into consideration residential electricity prices, commercial charging prices, tax rates levied on fuel and EVs, fuel economy for popular models in each vehicle segment, and the allowance for travel to commercial charging stations.

“The analysis considered four categories of real-world costs for both ICE and EVs, including energy, taxes, pump or charger, and deadhead miles,” the study states.

The study found trucks cost about the same to fuel and charge, while entry and midlevel cars and SUVs cost more to charge at home and in public than they do to fuel at a gas station.

“Luxury cars and SUVs fall somewhere in the middle,” he said. “Of course, gas prices can fluctuate and electricity costs vary widely by region depending on how it is produced.”

Chauhan, citing Kelley Blue Book data, said cost parity between electric vehicles and internal-combustion engine cars is largely lacking—EVs are generally more expensive—with an average transaction price of $53,438 in June versus $48,808 for ICE vehicles.

Additional Findings

The Anderson Economic Group further found the following:

  • Entry-priced cars and crossovers. “In the entry-priced segment, gas-powered cars were the most economical to fuel at around $9.78 per 100 purposeful miles. That’s significantly more affordable than an entry-priced EV charged mostly at home ($12.55), and it’s a dramatic savings over an EV charged mostly at commercial charging stations ($15.97),” the report states.
  • Mid-priced cars and crossovers. “ICE vehicles were also more affordable to fuel in this segment, at approximately $11.08 per 100 miles. This cost is lower than that for primarily home EV charging ($12.62) and for mostly commercial EV charging ($16.10),” according to the report.
  • Luxury-priced cars and crossovers. “In the luxury segment, electric vehicles charged mostly at home were the most economical. High-end EV drivers paid around $13.50 per 100 miles, as opposed to the $17.56 it would have cost to fuel a comparable ICE car. Luxury EV drivers charging mostly commercially, however, paid slightly more than they would have in an ICE vehicle ($17.81),” the report states.
  • Pickup trucks. “At around $17.10 per 100 miles, diesel-powered trucks were less expensive to fuel than their gas or electric counterparts. Gasoline-powered pickups cost about $17.58 to fuel, while EV trucks charged mostly at home cost $17.72. Drivers of electric pickups who needed to charge commercially most of the time found themselves paying about $26.38—exceeding their diesel counterparts by about $9,” according to the report.
Sumit Chauhan

Sumit Chauhan

‘Not As Much as People Think’

“So, the savings are not as massively different as people think,” Chauhan said.

When it comes to the two forms of EV charging—the public chargers and the at-home chargers, Chauhan told CUToday.info, “The issues are slightly different between each of them. The issue with public charging is how do I know which is the one that is closest to me while I'm driving and I'm running out of charge, and how much would it cost me to go and charge there,” he said.

And, of course, different types of chargers re-charge vehicles faster than others.

Charge-Buddy?

Chauhan said he expects that in the near future there will be apps, like Gas Buddy, that will be available for EV charging stations.

“You will see which are the lowest cost and help you optimize the number of hours that you spend charging at a public charging station,” he said, with the objective being to save people money.

Meanwhile, when it comes to home chargers, where most of the charging takes place, Chauhan said some challenges exist.

“Let's say you work nine to six. You come back at six, plug in your car in your garage. What is happening today is the car starts charging immediately after you plug it in,” he explained. “But your car is plugged in the whole night. Why do you need to charge it at 6 p.m. when probably the electric rates are at their highest. The ideal thing to do is, if you know that you're not going to drive till 6 a.m., charge between 3 a.m. and 6 a.m. when rates are the lowest.”

‘Jacking Up Rates’

Such tools are already available, noted Chauhan, who suggested that’s important as the price for electricity is only going to increase.

“Right now, the government is giving a lot of thought towards electrification of cars. But, as the number of electric vehicles increases and the amount of electricity being consumed markedly increases, they will start jacking up the rates.”

Then there is another factor Chauhan believes will help drive up electricity costs, and that is that EVs do not generate the kinds of fuel taxes used to pay for road maintenance.  

“Each time you fill your tank there is a small percentage of that price that goes towards the road tax. Right now, because the government is focusing a lot on electrification, people who are charging their electric cars are not paying for the road tax,” Chauhan said.

At some point that tax will also be passed along at charging stations and at homes, Chauhan noted.

“The whole intention is to move people to electrification, because it's cleaner and supposedly better than what we have today. But the cost side of this will catch up with consumers,” Chauhan said.

‘Even Worse’

Another concern for EV owners today is the possibility of non-standard charging stations not working the same for all of EV batteries. Chauhan said that may lead to a public charger damaging EV batteries.

“Even worse, it could possibly impact the car’s electrical system,” he said.

Chauhan anticipates standards will eventually be developed for charging stations, but for now, it’s a issue that goes beyond just a concern for EV owners—it’s also potentially problematic dor lenders for which the vehicles are collateral.

“Lenders would be wise to give their new EV borrowers a booklet on how to best use public charging stations and how to take advantage of the lowest electric rates when they are at home,” Chauhan advised. “That will not only help to protect the borrower, but the lender, as well.”

Chauhan further advised lenders to really understand the warranty contracts on battery cells for each EV they finance.

“The major repair concern with an EV is the battery cells,” reminded Chauhan. “Whoever the maker of the cell is, the lender needs to review those warranties carefully. As I said before, what happens if an EV charging station, or even owner error, damages the battery.”

Varied Costs

Just as the Anderson Economic Group study pointed out, operating costs to run an ICE vehicle 100 miles depend a great deal on the make and model of the car, which also holds true with an EV.

Data show that across the entire Tesla range, for example, it could cost between $2.90 and $4.50 to drive 100 miles. Entry-priced EVs charged at stations cost $15.97 per 100 miles, reports have stated. Also, a June 2021, the Department of Energy conducted a study to compare the maintenance costs of EVs and ICE vehicles. Overall, the DOE found that an EV costs 6.1 cents per mile driven, whereas an ICE vehicle costs 10.1 cents per mile driven.

Wednesday, September 27, 2023

FDNY deaths from 9/11 illnesses now equal those killed in the attack


NEW YORK  – It’s a number that nobody wanted to see repeated, but 343, the number of New York City firefighters who lost their lives on 9/11, is now the number of FDNY employees who have lost their lives from illnesses related to that fateful day and its aftermath.

The FDNY commissioner and union leaders alike said that number will only grow with time, which is why they also said it’s imperative that resources to care for first responders from 9/11 stay fully funded.

At a late morning news conference at his headquarters, Uniformed Firefighters Association of Greater New York (UFA) President Andrew Ansbro joined the leader of the city’s other major firefighters’ union, Jim Brosi of the Uniformed Fire Officers Association (UFOA), to mark the milestone.

They said the situation is tragic for their union members in general, but it feels all the more heartbreaking for the families of the recently departed.

“His life and his retirement was cut short,” Ansbro said about Firefighter Robert Fulco, 73, who died over the weekend. He became the 343rd FDNY employee to perish from 9/11-related illnesses.

His death came days after that of Hilda Vannata, 67, an FDNY EMT who also suffered from a 9/11 illness.

“We have long known this day was coming, yet its reality is astounding just the same,” FDNY Commissioner Laura Kavanagh said in a statement over the weekend.

“343 of our heroes lost in one day, and today, 343 more,” the statement continued. “The FDNY will never forget them. This is our legacy. This is our promise.”

Vannata and Fulco are part of what Ansbro described as a lengthening list of people getting sick in the two decades since the Sept. 11 attacks.

“There’s an entire whole host of cancers and lung illnesses that affect our members,” Ansbro said. “The number of illnesses keeps growing, and the number of people affected keeps growing.”

It’s why he and Brosi said the need is greater than ever to advocate for thousands of people who were in Lower Manhattan in the weeks and months after 9/11.

Currently, they said, more than 3,000 current or former FDNY workers have some type of cancer. About 8,000 more have some other illness related to their work in Lower Manhattan after the terror attacks.

Right now, the federal 9/11 victims’ health and compensation programs are fully funded, the union presidents said, but they added that the programs need to be regularly refunded by Congress.

The need, going forward, just like the number of people getting sick, will increase. That fact, said Brosi, has him and other advocates concerned, relative to another fact.

“We asked for over $2 billion last year,” he said about his union’s lobbying for funding in Congress, “and we got $600 million.”

He added that Congress needs to make a greater effort in the years ahead to provide assistance at the rates requested.

Romney FCU Selects Dolphin Debit to Manage ATMs

ROMNEY, W.V.–Romney Federal Credit Union  has selected Dolphin Debit to manage its ATMs.

Romney FCU

“We wanted an ATM to better serve our membership after hours and on weekends,” said Beth McDonald, CEO of Romney FCU. “We didn’t have the staff or experience to take on all the vendors, compliance and troubleshooting issues. 

McDonald and the staff at Romney turned to Dolphin to provide a solution.

“Dolphin consulted with us on a plan and delivered,” she said. “We have an ATM that provides great access, and we don’t have to worry about it. Dolphin takes care of everything. We have been very pleased with their service and response.” 

A ‘Perfect Fit’

Added Joe Woods, SVP-marketing & partnerships at Dolphin Debit, “ATM outsourcing for smaller credit unions and community banks is a perfect fit. Branch staff should be focused on the account holder. Managing an ATM in-house puts too much burden on staff with managing vendors, compliance, and other issues. Dolphin takes care of all the nuisance work and operations.” 

For info: www.dolphindebit.com

Monday, September 25, 2023

Involved in a data breach? Here’s what you need to know

 A bowl of multicolored cereal hoops spilled on a white floor

Posted: September 21, 2023 by

If you've received a message from a company saying your data has been caught up in a breach, you might be unsure what to do next. We've put together some tips which should help you when the (more or less) inevitable happens.

1. Check the company’s advice

Every breach is different, so check the company's official channels to find out what's happened and what data has been breached. Organizations often put out a rolling statement on their website, blog, or X (Twitter). Follow any specific advice they offer first, and keep an eye out for any further communications.

2. Change your password

If your password has been caught up in a breach, you should immediately change it. If you've used the same password on another site or service then you also need to change that. Cybercriminals will often try one password on multiple sites because they know people reuse them, so make sure you use a different password for every single site you have an account on. If you don't already use one, it's worth considering a password manager, which will generate and store passwords for you so you don't have to remember them all in your head.

3. Enable multi-factor authentication

Multi-factor authentication (MFA) adds an extra layer of security when logging in to your online accounts, and stops anyone from logging in with just your password. One of the most common ways of adding MFA to your online accounts is with an app—such as Google Authenticator, Authy, or Microsoft Authenticator—which generates a code that you enter into the site you're logging into. You can also use SMS MFA, where you are sent a code via text that you then enter into the website, or a hardware key such as a YubiKey which you plug into your computer. 

It's worth bearing in mind that a code can be phished as easily as a password so code-based MFA can't protect you from phishing, but it's still much better to have it turned on than not use it at all. Remember to never give an MFA code to anyone else, even if they pressure you into revealing it.

4. Freeze your credit report

If you're in the US, a credit freeze stops new creditors and potential thieves from accessing your credit report. Credit freezes must be set (and removed) at each of the three bureaus.

5. Set up credit monitoring

Credit monitoring tracks your credit report and borrowing behavior and alerts you if anything changes. A breached company may offer this as a service to you, but you can also get different levels of monitoring solutions, depending on your individual need.

6. Watch out for scammers

Scammers often try to take advantage of data breaches. They know that the breached company is likely to be contacting victims, and that the victims will be looking out for emails from the company. It's easy to spoof an email to make it look like it comes from somewhere else, and then send someone malware or a link to a phishing site.

We suggest you monitor the company's website for information about the breach and be very sceptical of messages that appear to come from that company. All the usual advice applies: Look for inconsistencies, odd email addresses, and strange links, and watch out for the two major red flags: urgency and a request for money or personal information.

Friday, September 22, 2023

Following Decision to Not Change Rates, Fed Chair Weighs In on 4 Key Economic Issues

WASHINGTON–With the Fed having opted to leave rates unchanged at its just-completed September meeting, Chairman Jerome Powel has offered some signals on how the central bank views a number of critical issues and for what might lie ahead.

Powell Jerome

Jerome Powell

As CUToday.info reported, the Fed  has left the target range for the federal funds rate at 5.25% and 5.50%. Some forecasters believe the Fed will raise rates once more this year—with the Fed itself indicating that is likely--while NAFCU Economist Noah Yosif predicted there will be “no further hikes in this cycle, with a rate cut arriving around the middle of next year.”

Four Key Issues

During a press conference held following adjournment of the meeting, Powell, along with a statement issued by the Fed, touched on four key themes, including:

  • Interest Rates. Powell made clear that as long as the economy is growing at a healthy pace, it would be premature to cut interest rates. By a 12-7 margin, Fed policymakers also expect to raise rates again, most likely this year.
  • Unemployment. Members of the Fed believe the current strong labor market will last into 2025, which could pose a challenge for efforts to fight inflation, especially if strong hiring leads to big wage increases.
  • Inflation. During his remarks Powell said progress has been made, but again stressed there is a “long way to go” to bring inflation down to the central bank’s 2% target.
  • Growth. The Fed is most optimistic when it comes to economic growth, forecasting Q4 GDP growth at 2.1% on an annualized basis, up from 1% at its June meeting. In addition, the Fed has boosted its 2024 GDP expectations.

NCUA Chairman Harper Welcomes Otsuka Nomination

WASHINGTON–President Biden has nominated Tanya Otsuka to serve on the NCUA board. Otsuka would fill the seat currently held by board member Rodney Hood, whose term expired in August.

Otsuka is currently senior counsel for the majority staff of the U.S. Senate Banking, Housing, and Urban Affairs Committee under Chairman Sherrod Brown (D-OH), where she has handled the committee’s work on banking and credit union issues since March 2020.  

Screen Shot 2023-09-21 at 4.41.46 PM

Tanya Otsuka

In 2019, she also served on the Committee staff through the Government Affairs Institute at Georgetown University’s Capitol Hill Fellowship Program, on detail from the FDIC, according to the White House.  

“Tanya Otsuka is a committed public servant and a well-qualified nominee to serve on the NCUA board,” said NCUA Chairman Todd Harper. “Tanya’s past work has strengthened the U.S. financial system, protected consumers, and advanced the ability of credit unions to innovate and compete. Tanya would also bring a different point of view to the work of the agency as the first Asian-American NCUA board member. If confirmed, I look forward to working with Tanya to protect the deposits of America’s nearly 138 million credit union members and to expand access to safe, fair, and affordable financial services to under-resourced communities. I hope the Senate acts quickly on her nomination.”

What's Ahead

According to Harper, over the the coming weeks Otsuka will be meeting with senior NCUA staff and begin preparations for her confirmation hearing as part of a process to be overseen by NCUA Chief of Staff Catherine Galicia and other agency offices.

"I am also very grateful for Board Member Rodney E. Hood’s continued service on the NCUA board," said Harper. "His institutional knowledge and commitment to financial innovation and inclusion are hallmarks of his leadership over the last four years. Together, we have advanced important priorities for credit union members across the country, including adoption of today’s final rule on financial innovation."

For Hood it marks the completion of his second term on the board.

Other Nominees

In addition to Otsuka, the president has also nominated:

  • Melissa G. Dalton, to be Under Secretary of the Air Force, Department of Defense
  • Andrew Plitt, to be Assistant Administrator for the Middle East, U.S. Agency for International Development
  • Spencer Bachus III, to be Member (Republican) of the Board of Directors of the Export Import Bank of the United States

CUNA Issues Statement

“We congratulate Ms. Otsuka on her nomination to the NCUA Board,’ said CUNA President/CEO Jim Nussle. “CUNA, leagues, and credit unions have plenty of work to accomplish in collaboration with NCUA, and we look forward to working with her if she is confirmed.” 

Virginia League Statement

"The Virginia Credit Union League looks forward to working with Ms. Otsuka should she be confirmed," said League President/CEO Carrie Hunt. "We are very excited to see how she will bring her talents to the credit union industry."

Thursday, September 21, 2023

NCUA Board Approves Final Rule on Financial Innovation


NCUA Express


Wednesday, September 20, 2023

The Federal Reserve left interest rates unchanged but stayed open to an increase before the end of the year.

 Recent indicators suggest that economic activity has been expanding at a solid pace. Job gains have slowed in recent months but remain strong, and the unemployment rate has remained low. Inflation remains elevated.

The U.S. banking system is sound and resilient. Tighter credit conditions for households and businesses are likely to weigh on economic activity, hiring, and inflation. The extent of these effects remains uncertain. The Committee remains highly attentive to inflation risks.

The Committee seeks to achieve maximum employment and inflation at the rate of 2 percent over the longer run. In support of these goals, the Committee decided to maintain the target range for the federal funds rate at 5-1/4 to 5-1/2 percent. The Committee will continue to assess additional information and its implications for monetary policy. In determining the extent of additional policy firming that may be appropriate to return inflation to 2 percent over time, the Committee will take into account the cumulative tightening of monetary policy, the lags with which monetary policy affects economic activity and inflation, and economic and financial developments. In addition, the Committee will continue reducing its holdings of Treasury securities and agency debt and agency mortgage-backed securities, as described in its previously announced plans. The Committee is strongly committed to returning inflation to its 2 percent objective.

In assessing the appropriate stance of monetary policy, the Committee will continue to monitor the implications of incoming information for the economic outlook. The Committee would be prepared to adjust the stance of monetary policy as appropriate if risks emerge that could impede the attainment of the Committee's goals. The Committee's assessments will take into account a wide range of information, including readings on labor market conditions, inflation pressures and inflation expectations, and financial and international developments.

Voting for the monetary policy action were Jerome H. Powell, Chair; John C. Williams, Vice Chair; Michael S. Barr; Michelle W. Bowman; Lisa D. Cook; Austan D. Goolsbee; Patrick Harker; Philip N. Jefferson; Neel Kashkari; Adriana D. Kugler; Lorie K. Logan; and Christopher J. Waller.

For media inquiries, please email media@frb.gov or call 202-452-2955.

Implementation Note issued September 20, 2023

With Fed to Announce Rate Decision Today, New Fannie Mae Report Says 1 Big Question Remains Unanswered

WASHINGTON—With the Federal Reserve’s Open Market Committee set to conclude its two-day meeting today, most analysts are expecting it to stand pat and not raise rates. But with underlying inflation decelerating and signs that the labor market is cooling, the central question for economists remains whether the economy is headed for a soft landing or a mild recession, Fannie Mae reported.

According to the September 2023 commentary from the Fannie Mae Economic and Strategic Research (ESR) Group, “mixed signals” from key economic data releases continue to muddle the near-term outlook – and the answer to that question – but a modest contraction remains the most likely outcome as consumption continues to outpace incomes and previous monetary policy tightening works its way through the system, Fannie Mae said.

“Significant divergence between gross domestic product (GDP) and gross domestic income (GDI) over the past three quarters increases the risk that the ESR Group’s 2023 GDP forecast, which was upgraded this month by three-tenths to 2.2% on a Q4/Q4 basis, will come in lower than currently expected,” Fannie Mae explained. “Regardless, the ESR Group notes that robust consumption growth in July was likely due to a series of temporary factors, and credit card transaction data and control group retail sales suggest real consumption growth will pull back in August.”

econoutlook092023a

‘Renewed Headwinds’

The housing market faces “renewed headwinds” with mortgage rates settling above 7%, according to the ESR Group. Still, the downside risk to total home sales is limited as more sales are being driven by life events rather than discretionary factors, and the cash share of purchases remains high. New home sales were “surprisingly strong” in the first half of the year, due partly to homebuilder rate buydowns, which become more expensive when mortgage rates rise, Fannie Mae stated.

Going forward, the ESR Group said it expects new home sales to pull back slightly due to the higher mortgage rate environment and recent decline in homebuilder confidence.

‘Unforeseen Support’
“In April 2022 we noted our expectation that the combination of dissipating stimulus impact and tightening monetary policy would result in a mild recession in the second half of 2023; mild in part because we expected the housing supply shortage to keep production from falling significantly,” said Doug Duncan, Senior Vice President and Chief Economist, Fannie Mae. “Housing production has indeed held up. However, the pandemic-related fiscal transfers and built-up household savings have supported consumer spending longer than we had expected, providing unforeseen support to the macroeconomy.

“Our current prediction for a mild downturn in the first half of 2024 is predicated on the belief that consumers will begin pausing their spending, in part due to the exhaustion of those funds and having to realign to a more sustainable relationship between spending and incomes.

Households Remain ‘Confident’

“According to our latest National Housing Survey, households remain confident in their own employment, even though they don’t feel great about the overall economy, and the vast majority don’t believe it’s a good time to buy a home, as mortgage rates and home prices continue to constrain affordability,” Duncan continued. “This is evidenced by recession-level home sales volumes resulting from the very low levels of existing homes for sale and the significant affordability challenges. The elevated share of new homes relative to total home sales and a similarly elevated share of first-time homebuyers purchasing new homes are additional evidence of the ongoing housing supply problem. We expect that total housing market activity will remain at a low level into 2024 as the Federal Reserve continues to hold the line on interest rates against inflation.”

Thursday, September 14, 2023

One Thing Helped Fuel CPI Increase; Here’s CU Economists Are Responding

WASHINGTON–Thanks to a jump in the price of gasoline, the Consumer Price Index climbed 3.7% in the year through August, according to new data from the Bureau of Labor Statistics. 

The new number is likely to lead to wariness at the Fed as it ponders the direction of rates later this month, as the August CPI figure was faster than the 3.2% July reading and the 3.6% that economists had expected, according to analysts. 

Yosif, Noah

Noah Yosif

Categories also seeing cost increases in the new CPI data included airfares, car insurance and auto repairs. 

"Headline inflation rose by 0.4% month-over-month due to a spike in energy prices, suggesting there is still progress to be seen in restraining inflation,” said NAFCU Economist Noah Yosif. “The Fed will likely seek additional data to confirm a temporary or an extended spike in headline and, potentially, core inflation as higher energy prices permeate throughout the broader economy, thus the expectation of a pause in tightening when the committee meets next week remains in place.

“Nevertheless, this was a report that nudges the FOMC towards a more hawkish position. NAFCU believes that even if future inflation data continues to exceed expectations, it is more likely to compel the FOMC to leave rates at their present level for longer, rather than forcing more rate hikes."

CUNA: No Reasons to Increase Rates

Kebede, Darwit

Dawit Kebede

“The headline inflation over the past 12 months increased by 3.7% in August, faster than the 3.2% increase in July due to high gas prices. Gas prices were 11% higher in August,” said Senior Economist Dawit Kebede. “Core inflation – which excludes volatile gas and food prices – slowed down to 4.3% from 4.7% in July, relative to a year ago.  Core prices also ticked up slightly higher on a monthly basis by 0.3% after two consecutive months of 0.2% increase in June and July. This is equivalent to a 2.8% percent annualized increase based on average price growth of the last three months. It indicates core inflation is still trending down in the right direction to the Federal Reserve's target despite the slight uptick in August. 

“The Federal Reserve is expected to hold rates steady when they meet later this month. Recent labor market reports indicate a better balance in labor demand and supply as hiring slowed down and labor supply increased, raising the unemployment rate higher,” Kebede continued. “There is nothing in this inflation report that will prompt the Federal Reserve to increase rates during their next meeting.”  

Wednesday, September 6, 2023

New Measure of Middle-Income Households Shows How ‘Deeply’ Inflation Has Been Felt / Fresh Today / CUToday.info

 cutoday.info

DULUTH, Ga. — A brand-new monthly index has been released that seeks to measure the purchasing power of middle-income households between $30,000-$100,000.

Compiled by financial services provider Primerica, the Primerica Household Budget Index (HBI) looks at the difference between the growth in earned income and the change in the costs for necessities like food, utilities, health care, and gasoline to understand how the current economy is impacting middle-income households’ ability to maintain a budget, according to the company.

It also evaluates whether there are opportunities for middle-income families to save money or pay down debt versus using savings or increasing debt, Primerica added.

Primerica 1

Primerica explained the HBI data is presented as a percentage. 

How Index Works

“When the index is above 100%, this means middle-income households may have extra money left over at the end of the month that can be applied to things like entertainment, extra savings, or debt reduction,” the company said. “If it is under 100%, households may have to reduce overall spending to levels below budget, reduce their savings, or increase debt to cover expenses.​ The index uses January 2019 as its baseline. This point in time reflects a recent ‘normal’ economic time prior to the COVID-19 pandemic.”

According to Primerica, between 2014 and 2020, the HBI results recorded steady gains in purchasing power for middle-income families, with a peak of 102.8% in November 2020.

“This means that compared to January 2019, households were in a stronger financial position to pay their monthly bills because wage growth outpaced the cost of everyday goods,” Primerica said. “Increasing inflation then caused the index to plummet. In June 2022, it reached a low of 85.6%.”

In July 2023, the index rose slightly to 97.5% from 97.0% in June 2023.

Primerica 2

‘Deeply Affected’

“The July index illustrates how deeply middle-income households were affected by the recent period of high inflation in which their income gains fell behind the rising cost of living expenses,” said Amy Crews Cutts, economic consultant to Primerica. 

Primerica reported that since the baseline of January 2019, the average middle-income household has cumulatively spent around $3,150 more than budget on basic necessities. In line with this, if the pandemic and ensuing inflation would not have been a factor, the HBI today would be closer to 110%, the company stated.

“Middle-income households finally are pulling ahead, but the last 18-months of inflation has caused many to fall behind which accounts for the rising credit card debt we are currently seeing,” said Cutts.

‘No Consistent Measure’

In releasing its new measure, Primerica said there is not currently a consistent measure to track middle-income households’ purchasing power.

“While the Consumer Price Index (CPI) provides a comprehensive measure of inflation, it does not offer a clear picture of how the change in prices of necessities impacts middle-income households because it is weighted to include all income levels and aggregates expenses for rarely purchased items, as well as expenses for which households can plan,” Primerica said. “The HBI removes infrequently purchased or predictable expense items and focuses solely on the purchasing patterns of middle-income households, defined as those with incomes of $30,000-$130,000.”

Tuesday, September 5, 2023

Even as Economy Remains Stronger Than Projected, Fannie Mae Forecast Still Sees ‘Eventual Downturn’

WASHINGTON—Recent economic data points to a stronger economy than previously expected, but the current business cycle “contours” still point to an eventual downturn, according to the August 2023 commentary from the Fannie Mae Economic and Strategic Research Group.

Given the “recent flurry of strong consumption data combined with two consecutive months of annualized Consumer Price Index (CPI) measures coming in close to the Fed’s 2% inflation target,” the ESR Group noted that the odds of a “soft landing” have increased, Fannie Mae said.

However, the ESR Group added, the full lagged effects of monetary policy tightening are still working their way through the economy.

thumbnail_ESR August

The ESR Group analysis, for example, said wage growth also likely remains too high to be consistent with 2% inflation over the long run, which it believes will keep monetary policy tight. Additionally, the ESR Group posited that the recent rise in medium- and longer-term Treasury yields will likely weigh on interest-rate-sensitive sectors in coming quarters.

The ’If’ and the ‘When’

While the ESR Group noted that both the “if” and “when” of a recession are uncertain given the strength of recent economic data and decelerating inflation, their baseline forecast is for one to occur, now expected to begin in the first half of 2024, Fannie Mae said.

Regardless of whether the economy enters a recession, the ESR Group is forecasting home sales will remain subdued within a tight range.

If the economy avoids a recession, the ESR Group said it expects home sales activity would continue to be suppressed by a lack of existing home inventory for sale combined with continued affordability constraints and homeowners remaining “locked in” to their low mortgage rate.

The Alternative

Alternatively, if the economy enters a recession, improvements in affordability and inventory stemming from likely lower interest rates is expected to be offset at least in part by a weaker labor market, tighter credit, and worsened consumer confidence, Fannie Mae said.

“Regarding new homes, both sales and construction have performed comparatively well despite higher mortgage rates to date; however, the ESR Group notes some downside risk given mortgage rates are again near 7% and homebuilder confidence pulled back in August,” Fannie Mae said.

Easy to Run ‘Aground’

“It is easy to run your forecast ship aground by underestimating the American consumer,” said Doug Duncan, senior vice president and chief economist at Fannie Mae. “Despite reduced saving, increased rollover credit card balances, and rising credit costs, consumers are sustaining consumption, supported by a decline in inflation.

“Nonetheless, tightening monetary policy takes a toll,” continued Duncan. “Will it result in a recession? Our base case forecast is a mild recession, and it looks as though the alternative is a soft landing, which is slow growth with only a small increase in unemployment. The difference between those two alternative outcomes is not expected to make much difference to home sales. The risk to housing activity is that inflation has bottomed out and begins to reaccelerate, requiring additional tightening from the Fed.”

Ivory Tower IOUs (student loans)

  Ivory Tower IOUs    More than 40% of US adults who pursued education beyond high school have ...